


Account reconciliation is the process of comparing your internal accounting records against external sources, such as bank statements, payment processor payouts, and platform settlement reports, to confirm that both sets of figures agree. For a multi-channel setup, that comparison covers several systems at once, and each one reports fees, payout timing, and settlement formats its own way.
A single bank deposit can represent hundreds of orders, minus platform commissions, processing fees, refunds, and withheld taxes. Matching those deposits back to individual sales by hand turns month-end into a multi-day spreadsheet exercise. APQC research published in April 2026 puts the median annual close at 18 days, while top-performing organizations finish in 10 days or less.
This guide explains account reconciliation in plain terms, covers the seven types of reconciliation with worked dollar examples, outlines the five-step account reconciliation process, and shows how to reconcile accounts across multiple sales platforms without manual spreadsheet matching.
TL;DR
- Accounting firms can scale reconciliation by standardizing templates, mappings, and SOPs across clients using the same platform stack.
- Account reconciliation compares a general ledger balance with an independent source and explains every difference.
- The process follows five steps: verifying the ledger, comparing supporting records, investigating discrepancies, posting adjustments, and closing the period.
- Common reconciliation differences include timing issues, missing entries, duplicates, unauthorized transactions, and amount mismatches.
- Multi-channel ecommerce reconciliation works best with a separate clearing account for each sales or payment platform.
- Automation reduces manual matching by flagging exceptions and tracing discrepancies back to source transactions.
- Reconciled accounts support reliable financial statements, audit readiness, and a more controlled close process.
What is account reconciliation?
A completed account reconciliation shows the book balance, the corresponding source balance, every reconciling item between them, and any adjustments needed to bring the records into agreement. It also provides supporting documentation and an audit trail for the period.
Source: Investopedia
Checking account reconciliation requires two pieces of data to match. The first is the business owner’s records (the books), and the second is a third party, such as a bank (bank statement). If you match up these two reports, you should see zero difference between the documents, which means they have the same value on a specific date.
The account reconciliation definition widens once sales move online. For a multi-channel seller, the third-party record is not one bank statement but a set of them: the Shopify payout report, the Amazon settlement report, the Stripe balance transaction export, and the PayPal transaction report, each covering a different slice of the same month. Reconciling accounts in that setup means proving that gross sales, platform fees, refunds, and taxes recorded in the general ledger add up to the net amount the bank actually received.
Business account reconciliation therefore covers far more than the checking account. A seller running four channels performs reconciliation of accounts across every platform clearing account, the checking account, and the fee and tax accounts underneath them.
A few related terms do mean different things, and those are worth pinning down.
| Term | Definition |
| Account reconciliation | Comparing a general ledger account balance against an independent external record and explaining every difference. |
| Accounting reconciliation | The same process named from the finance function’s side. Teams reconcile accounting records against the source documents behind them. |
| Bookkeeping reconciliation | The same mechanics at the bookkeeping level, covering bank, credit card, and clearing accounts. Also called reconciliation in bookkeeping. |
| Financial statement reconciliation | Tying every balance reported on the income statement and balance sheet back to its supporting schedule. |
| Reconciled balance | An account balance traced to supporting evidence and agreed to an external source. |
| Reconciling item | A difference between two records that is identified, explained, and either corrected or carried forward. |
Account reconciliations are inevitable for any business. The only difference is in the frequency. Usually, the bigger the company, the more frequently you need to reconcile the books with your bank statement: monthly, weekly, or even daily. Smaller businesses can go through the process every month or even every six months.
Why is account reconciliation important enough to repeat every period? Because the close cannot finish without it, and close speed is the clearest measure of how well the process runs.
→ To fully understand the whole accounting process inside one’s business, read our article on the AR basics.
What is the purpose of reconciliation?
The purpose of account reconciliation is four things: accurate records, internal control, regulatory compliance, and audit readiness.
Each does distinct work:
- Accuracy of financial records
Errors that enter through data entry, duplicate imports, or uncaptured platform fees stay in the ledger until a reconciliation finds them, and every report built on that ledger carries them until then.
- Internal control
Reconciliation acts as an internal control mechanism that ensures financial transactions are properly authorized and recorded.
- Compliance with regulations
Many regulatory bodies require companies to perform regular reconciliations to comply with accounting standards and legal requirements. Under U.S. GAAP, a reconciled general ledger is what supports the balances reported on the financial statements, so an unreconciled account undermines every figure derived from it.
- Preparing for audits
Regular reconciliations make the audit process smoother and more efficient, as they ensure that the accounts are accurate and up-to-date.
Good to know: APQC’s April 2026 research on the annual closing process puts top-performing organizations at 10 days or less, the median at 18 days, and slower performers at 35 days. The same research reports that 31% of organizations actively use AI in record-to-report processes, with a further 39% in the early stages of adoption. explained by the fact that the manual accounts reconciliation process is slow in identifying transactions that actually require special attention.
Types of reconciliation
There are seven common types of reconciliation in accounting:
- Bank reconciliation
- Accounts receivable reconciliation
- Accounts payable reconciliation
- General ledger reconciliation
- Tax reconciliation
- Intercompany reconciliation
- Credit card reconciliation
Each one compares a different internal record against a different external source, and most businesses run several of them inside the same monthly close.
The list below explains what accounts need to be reconciled in each case, with a worked example for every type.
#1. Bank reconciliation
This type of reconciliation helps businesses identify transactions recorded in their bank statements that have not yet been entered in the business’s own financial records. Common discrepancies include bank fees, direct debits, or deposits in transit (i.e., amounts received but not yet cleared by the bank).
Example:
The account reconciliation example below uses a multi-channel store instead of a single-account business, because that is where the differences get interesting.
A store processes 2,000 orders in March through Shopify, with payments settled by Stripe. The general ledger cash account shows $184,600 of gross sales for the month, while the bank statement shows $179,240 received. Four reconciling items explain the $5,360 difference: a $3,885 Stripe payout initiated on March 31 that cleared on April 2, $1,310 in Stripe processing fees deducted before payout, a $150 customer chargeback, and the $15 dispute fee charged alongside it.
Adjusting journal entries record the processing fees as an expense and reverse the chargeback against revenue. The payout in transit is carried as a reconciling item and clears in the following period, which brings the adjusted bank balance and the adjusted cash account into agreement. This reconciliation in accounting example shows the pattern behind most ecommerce differences: timing, fees, and disputes, in that order of frequency.
#2. Accounts receivable reconciliation
This type of reconciliation ensures that the amounts recorded in the accounts receivable ledger accurately reflect all outstanding invoices due from customers and match the total reported on the balance sheet. It also involves verifying that all payments received have been properly accounted for and that any discrepancies due to returns, allowances, or write-offs are correctly recorded.
Example:
A company’s accounts receivable ledger shows a total of $20,000, but the balance sheet shows $19,500. On reconciliation, it’s found that a recent payment of $500 was received but not posted to the accounts receivable ledger. The adjustment would be made to reflect this payment, aligning the ledger with the balance sheet.
How to reconcile accounts receivable:
- Post the adjusting journal entries and confirm the aging report and the control account now agree.
- Pull the accounts receivable aging report as of the period end date.
- Compare the aging total to the accounts receivable control account balance in the general ledger.
- Trace each difference to its source document: an unposted cash receipt, a credit memo, an unbilled shipment, or a write-off that was approved but never recorded.
#3. Accounts payable reconciliation
This type ensures that all amounts the company owes to suppliers and other creditors are accurately recorded in the accounts payable ledger and match the corresponding entries on the balance sheet.
Example:
The accounts payable ledger of a business shows liabilities totaling $15,000, whereas the balance sheet indicates $16,000. Reconciliation reveals an invoice for $1,000 that was received and not yet entered into the accounts payable system. The ledger is then updated to include this outstanding invoice.
How to reconcile accounts payable:
- Pull the accounts payable aging report and the vendor statements for the period.
- Compare the aging total to the accounts payable control account in the general ledger.
- Investigate each difference: an unrecorded vendor invoice, a payment applied to the wrong vendor, a vendor credit memo not yet entered, or a duplicate bill.
- Post the adjusting journal entries and confirm the subledger ties to the control account.
→ Check an ultimate guide to the full cycle AP process.
#4. General ledger reconciliation
This involves ensuring that all entries in the general ledger are complete and accurate, and that the ledger balances reconcile with subsidiary ledgers and other financial reports.
Example:
During the reconciliation of the general ledger, it’s noticed that the total sales recorded do not match the sales tax collected. Upon investigation, it is found that sales totaling $2,000 were recorded without adding sales tax. Corrections are made to include the tax, thus aligning the sales records with tax liabilities.
#5. Tax reconciliation
Tax reconciliation involves ensuring that all tax-related entries in the financial records match the amounts actually paid or to be paid as per tax returns. This includes verifying tax liabilities, credits, and deductions.
Example:
A company’s records show that $50,000 was paid in corporate taxes, but the tax return prepared indicates a liability of $48,000 due to an additional deduction that was not initially recorded. The reconciliation process would involve adjusting the financial records to reflect this deduction, ensuring that the records match the actual tax liability and purchases.
#6. Intercompany reconciliation
In companies with multiple departments or entities, this reconciliation ensures all transactions between these entities are recorded consistently in all relevant ledgers.
Example:
Company A sells inventory to its subsidiary, Company B, for $10,000. Reconciliation ensures that Company A records this as revenue and Company B as an expense and that the transaction is eliminated during consolidation to prevent double-counting of revenue.
#7. Credit card reconciliation
This involves verifying credit card statements against purchase receipts and payment records in the business’s books.
Example:
A review of a company credit card statement reveals a charge of $300 for office supplies. Reconciliation involves ensuring there is a corresponding receipt and that the expense was recorded under the correct account.
What does reconciling an account involve?
Reconciling an account involves comparing the general ledger balance and its supporting subledger with an external record for the same period, then identifying and clearing any differences. Each unmatched amount becomes a reconciling item that must be classified before it can be resolved. The internal record may be an aging report, fixed asset schedule, or payment-platform clearing account; the external record is the corresponding statement or report issued by the counterparty.
The five reconciliation differences.
| Difference | What it looks like | How it resolves |
| Timing | A transaction recorded in one system before the other sees it: a payout initiated on the 31st that clears on the 2nd | Carried forward as an open item, clears next period |
| Missing entry | Something never recorded at all: a bank fee, a platform commission, a refund | Adjusting journal entry |
| Duplicate | The same transaction entered twice, often from an overlapping bank feed import | Reverse the second entry |
| Unauthorized | A charge nobody can trace to an approved purchase, including fraud | Investigate, dispute, then record the outcome |
| Amount mismatch | Both sides show it at different values: a processor deducted a fee the books did not capture | Correct to the external amount and book the difference |
What it leaves behind. A completed reconciliation produces a zero unexplained difference between the two balances, an updated general ledger, and a trail showing what was compared and why it differed. Approval by someone other than the preparer is what makes that trail hold up, and auditors ask for it first.
APQC’s April 2026 research found that 31% of organizations actively use AI in record-to-report processes, with another 39% in the early stages of adoption.
The next section explains how to reconcile an account in practice, step by step.
What are the steps in account reconciliation?
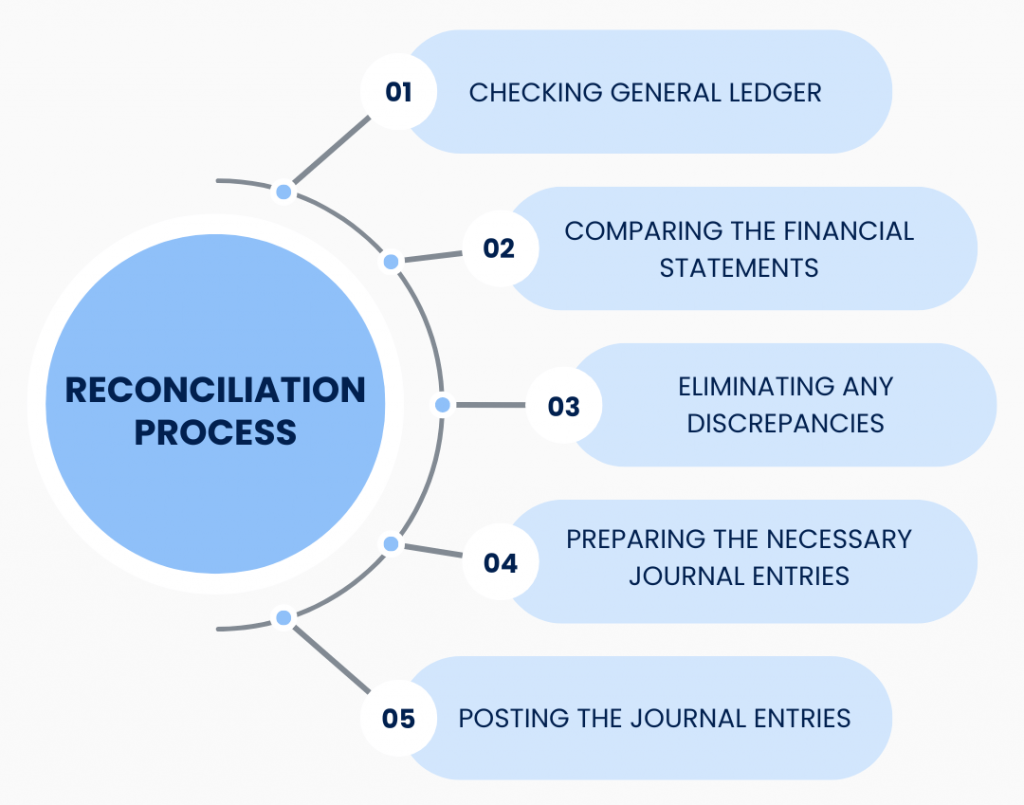
The account reconciliation process runs in five steps:
- Verify the general ledger balance
- Compare it with supporting records
- Identify discrepancies
- Resolve and document differences
- Post any required adjusting entries
The same sequence applies whether you’re reconciling one bank account or multiple platform clearing accounts, making it a repeatable checklist for the close.
Step #1: Checking general ledger
Accurate records are one of the most important steps that affect future reconciliations. Neglecting this essential step leaves your company’s finances open to manipulation and potential fraud. Even the smallest businesses need a system that reduces accounting errors and simplifies bookkeeping procedures.
So first things first. For an accurate account reconciliation, an accountant needs to go through all the general ledger accounts to verify that there are no missing transactions and that the balance is right.
Step #2: Comparing the financial statements
Then, for correct account reconciliation, the specialist has to compare the balance in the general ledger with data from independent third-party systems or other supporting documentation (bank or credit card statements). This can be a reconciliation of bank statements and balance sheets.
Reconciliation between the bank statement and the general ledger allows both statements to complement each other. Errors and omissions in the books are easily detected and rectified.
Step #3: Getting rid of balance discrepancies if such appear
Next, a professional studies the acquired information and takes appropriate corrective actions to eliminate any discrepancies in both the general ledger and bank statement.
Reconciliation tasks include checking balances, identifying duplicate entries, and correcting mistakes where necessary. These routines may seem like a lot of work, but they help keep the accounts neat so that a business owner can see clearly how the business performs.
Step #4: Preparing the necessary journal entries
It’s time to double-check your ledger and all the noted discrepancies. If discrepancies have been detected in the previous step of account reconciliation, balance errors should be corrected and marked in special journal entries.
Step #5: Posting the journal entries
And that’s it! Now, the journal entries are ready to be posted.
When a discrepancy between the two accounts is found (for example, because an amount was entered in one ledger but not in another or because both books show different values for a single transaction), a “secondary entry” has to be posted to correct it. Only by posting all necessary secondary entries can you achieve accurate reconciliation. After this step, the general ledger is updated for the reconciliation period.
Account reconciliation best practices
Account reconciliation best practices standardize how accounts are matched, documented, reviewed, and cleared during each close. A consistent process makes reconciliations easier to review, repeat, and audit.
- Reconcile to a fixed cutoff date and hold it for the whole close.
- Separate preparer and reviewer on every reconciliation, so no one signs off on their own work.
- Age unresolved reconciling items and escalate anything older than 60 days.
- Attach supporting documents to the reconciliation itself instead of filing them separately.
- Standardize the reconciliation process accounting teams follow across every account, so a reviewer reads the same format each time.
Efficient account reconciliation comes from that repeatability: the same cutoff, the same format, and the same review path every period.
How to reconcile accounts across multiple sales platforms
To reconcile accounts across multiple sales platforms, you need to match individual orders, fees, refunds, and payouts back to each source. Shopify, Amazon, Stripe, and PayPal all report fees, settlement timing, and payout details differently, so using a separate clearing account for each channel makes it easier to identify where a discrepancy originated.
The safest structure is one clearing account per platform, reconciled against the sales date instead of the payout date, with fees mapped to their own account. Gross sales post to the clearing account, fees and refunds reduce it, and the payout moves the net amount to the checking account. Booking only the net payout skips all of that. The fees and refunds deducted before the transfer never reach the books, which understates both revenue and expenses by an estimated 2% to 4%.
Maintaining that structure across every channel is exactly what Synder is built for. The accounting automation platform from CloudBusiness Inc. connects 30+ sales and payment platforms to six accounting destinations, and its auto-reconciliation tooling matches every line in each clearing account against the platform’s own records, automated via API for Stripe, Shopify, and Amazon, guided upload for PayPal, and custom column mapping for any other integration. Anything that does not tie 100% is flagged, so you review only the transactions that need attention.
Payout matching splits each deposit into its underlying charges, fees, refunds, and chargebacks, which is what keeps the gross figures intact. Balance Reconciliation checks a period against the platform’s reported starting and ending balances before summaries post to the books, with an audit trail you can download or revisit.
Dermeleve, which sells through Shopify, Amazon, wholesale, and Stripe, runs 170,000+ transactions through this structure and holds 99.5%+ reconciliation accuracy across all four channels, with monthly variance against QuickBooks Online under 0.5%.
Synder has allowed me to remain independent in my role and accomplish more things in less time. Knowing Synder has the bandwidth to add more channels as I continue to grow, without any additional cost, gives me the confidence I can continue to operate and grow without disruptions to my business operations.
Andy Pozniak, CFO at Dermeleve
For the full breakdown, covering how to normalize export formats, handle staggered payout cycles, and map platform fees channel by channel, see Synder’s guide to transaction reconciliation.
How automation simplifies reconciliation for ecommerce businesses
Manual account reconciliation holds up at low volume and breaks down as channels multiply. Exporting each platform’s activity into spreadsheets means normalizing column layouts by hand, aligning payout schedules against one bank feed, and separating fees from refunds from adjustments before a single line can be matched. Errors introduced at that stage are found weeks later, in the P&L or during audit prep, and correcting them means rebuilding the work.
Automation changes what a person actually reviews: every line becomes only the exceptions. Hybrid workflows that pair AI matching with deterministic rules are estimated to cut payout review time by 70% to 85%.
Synder users get that exception-only review from the auto-reconciliation feature, which adds:
- Discrepancies flagged inside Synder before they post, instead of surfacing during month-end close
- Every mismatch linked back to the source transaction that caused it
- The full transaction journey between the accounting platform and the sales platform, visible for investigation
- Entries rolled back, synced again, and the comparison re-run once corrected
- 50% less time on month-end close, across 100k+ transactions auto-managed per client
The direction of travel is clear across the profession. KPMG’s 2026 Global AI in Finance survey of 1,013 senior finance leaders found active AI use in the finance function rose from 30% to 75% in two years, with 71% reporting that it meets or exceeds ROI expectations.
Example: Automating Stripe payout reconciliation in QuickBooks Online
A QuickBooks Online bank feed shows a Stripe payout as one deposit, with nothing underneath it: no charges, no fees, no refunds, no chargebacks. Synder’s Stripe and QuickBooks Online integration closes that gap.
Once the two are connected, Synder creates the Stripe clearing account in QuickBooks. When Stripe withdraws money to the bank, Synder records a transfer from that Stripe account to Checking, mirroring the actual movement of funds.
QuickBooks then pre-matches the transfer to the bank statement line of the same amount, guessing which statement line corresponds to the transaction Synder created in Checking. Open the For Review list in QuickBooks Banking and click “Confirm” next to the Stripe withdrawal.
Note: You can’t create transactions in the Banking Tab when reconciling, as they may cause an error. Each transaction will be added only when it’s been approved by the bank.
The same sequence applies to Shopify, Amazon, PayPal, and every other connected channel, each with its own clearing account.
→ Read how to connect Stripe to QuickBooks to get a better understanding.
PlayYourCourt, a tennis coaching platform running Stripe into QuickBooks Online, previously had a bookkeeper spend 40 hours a month opening each transaction, checking its metadata, and categorizing it by hand. Automating that review saves the company 480+ hours and close to $24,000 a year.
Time is money. Instead of a bookkeeper spending 40 hours a month manually reviewing thousands of transactions each month, Synder does it all automatically, the moment the charge happens. Which means we save 480 hours and almost $24K yearly.
Justin McKelvey, Head of Product at PlayYourCourt
Reconciliation, GAAP compliance, and audit readiness
Why GAAP financials depend on reconciled accounts
Reconciliation is a prerequisite for GAAP-compliant financial statements, not a housekeeping task that follows them. The income statement and balance sheet are assembled from general ledger balances, so any account that has not been traced to supporting evidence carries an unquantified error straight into the reported figures. An auditor testing cash, receivables, or deferred revenue starts by asking for the reconciliation and the documents behind it, and an account with no reconciliation on file becomes a scope limitation rather than a tested balance.
Cash collected against revenue recognized under ASC 606
For subscription businesses, the distinction that matters most is between cash reconciliation and revenue recognition. Reconciling a Stripe payout to a bank deposit confirms the money arrived. It says nothing about how much of that money can be reported as revenue in the period, because under ASC 606 revenue is recognized as the performance obligation is satisfied. An annual plan collected upfront reconciles fully to cash in month one and recognizes across twelve months, which means the deferred revenue account needs its own reconciliation against the billing system’s schedule.
Accrual accounting widens what needs reconciling
The basis of accounting changes the scope of the work. Cash-basis reconciliation compares recorded receipts and payments to what moved through the bank. Accrual-basis reconciliation additionally ties the accounts that exist because timing and cash differ: accounts receivable, accounts payable, accrued liabilities, prepaid expenses, and deferred revenue. Those accounts are where unreconciled balances accumulate quietly, because nothing in the bank statement contradicts them, and they are where auditors concentrate their testing.
What unreconciled books cost at audit and diligence
The consequences of skipping this work arrive late and cost more than the reconciliation would have. Unreconciled books extend audit fieldwork, slow diligence during a funding round or acquisition, and in the worst case force a restatement of previously issued financials. Finance leaders are responding to that pressure: in Deloitte’s Q4 2025 CFO Signals survey of 200 North American CFOs, 50% named digital transformation of the finance function their top priority for 2026.
How do you reconcile a balance sheet?
Balance sheet reconciliation verifies that each balance sheet account agrees with supporting records and that total assets equal total liabilities plus equity.
- Gather supporting documents. Collect bank statements, invoices, loan statements, inventory records, fixed asset schedules, and other documents supporting balance sheet balances.
- Reconcile each account. Compare cash, receivables, inventory, fixed assets, payables, loans, accruals, and equity accounts with the corresponding records.
- Investigate discrepancies. Trace differences to missing transactions, posting errors, timing differences, or incorrect calculations, then record any required adjusting entries.
- Verify and document. Confirm the adjusted balances agree with supporting records and retain the reconciliation and adjustments for the audit trail.
Balance sheet accounts are typically reconciled as part of the month-end and year-end close.
What is a good balance sheet reconciliation?
A good balance sheet reconciliation verifies that every balance sheet account agrees with reliable supporting records and that any differences are identified, explained, and corrected.
A strong reconciliation should include:
- Complete coverage: Reconcile all asset, liability, and equity accounts, including prepaid expenses, accruals, and deferred revenue.
- Supporting evidence: Tie balances to bank statements, subledgers, invoices, loan statements, fixed asset schedules, and other source records.
- Documented differences: Record discrepancies, their causes, and any adjusting entries made.
- Timely completion: Perform reconciliations as part of the regular month-end or year-end close.
- Consistent procedures: Apply the same reconciliation methods from period to period.
- Review and approval: Have material reconciliations reviewed according to the company’s internal control procedures.
Example of a balance sheet reconciliation
Suppose XYZ Corporation is reconciling Cash and Accounts Receivable as of December 31, 2026.
| Account | General ledger | Supporting record | Difference | Resolution |
| Cash | $25,000 | $24,700 | $300 | Investigate outstanding items and bank adjustments |
| Accounts receivable | $10,500 | $10,300 | $200 | Record the unrecorded customer payment |
The accountant investigates each difference, records any required adjustments, confirms that the corrected ledger agrees with the supporting records, and documents the reconciliation for review.
How do you reconcile expenses?
Expense reconciliation compares expenses recorded in the accounting system with bank statements, credit card statements, receipts, invoices, and expense reports.
- Gather supporting documents. Collect bank and card statements, receipts, invoices, purchase orders, and expense reports.
- Compare recorded expenses. Match each transaction by amount, date, payee, and expense account.
- Investigate discrepancies. Look for missing expenses, incorrect amounts, misclassifications, bank fees, and duplicate transactions.
- Record adjustments. Add missing expenses, correct coding errors, and remove duplicates where necessary.
- Review and finalize. Confirm that the adjusted records agree with the supporting statements and document the completed reconciliation.
Expense accounts are commonly reconciled during the monthly close to keep financial records complete and accurate.
Reconciliation for accounting firms: scaling across multiple clients
For accounting firms serving ecommerce businesses, reconciliation gets harder to standardize as each client brings a different combination of sales channels, payment processors, and chart-of-accounts structures. Standardizing around the platform instead of the client is what makes the volume manageable, with one Stripe template, one chart-of-accounts mapping ruleset, and one SOP reused across every client on that stack.
The payoff is measurable at the practice level. LedgerZ Bookkeeping, which serves clients across software, construction, hospitality, and ecommerce, saves 10 hours per client each month on reconciliation and 120 hours a year on month-end close after standardizing its workflow with Synder, reclaiming three full workweeks annually.
Synder saves me at least 10 hours a month on manual data entry and reconciliation. It gives me the ability to manage multiple income streams and separate clearing accounts for different locations, making month-end close so much easier and more accurate.
Christina Testolin, Founder and CEO of LedgerZ Bookkeeping
This shift is a stated priority across the profession. The AICPA’s CPA Firm Top Issues Survey, conducted in April and May 2026 with 629 respondents, found that managing change driven by technology and AI ranked as the number one issue for firms of every size in terms of expected impact over the next five years.
For the full playbook on building firm-level reconciliation templates, see Synder’s guide to transaction reconciliation.
Summing up
Why is reconciliation important in accounting? Because it determines whether the financial statements can be trusted. Comparing internal records against bank statements, processor reports, and vendor statements, then explaining every difference, is what turns a set of ledger balances into reportable figures.
The work looks different depending on where you sit. An ecommerce seller reconciles a clearing account per sales channel against staggered platform payouts. A SaaS finance lead reconciles cash collected in one timeline and revenue recognized in another. An accounting firm reconciles the same platform stack across many clients and needs one repeatable template instead of many bespoke ones.
All three cases follow the same five steps and break down for the same reason, which is volume handled by hand. The remedy is the same as well: a fixed cutoff, every difference explained, and the evidence kept.
FAQ
What is reconciliation, in simple words?
Reconciliation is how you find and explain the gap between two records of the same money. Your accounting software says you took in $50,000 last month; your bank shows $48,500 arriving. Reconciliation is the work of proving where the $1,500 went: $1,100 in payment processing fees deducted before payout, $300 in customer refunds, and a $100 deposit still in transit. Once every dollar of that difference is identified and recorded, the account is reconciled.
What happens if you don’t do bank reconciliation?
Skipping bank reconciliation lets small errors accumulate into material misstatements that nobody catches until they are expensive to fix. Duplicate bank-feed entries, unrecorded fees, and missing deposits stay in the ledger, so the cash balance you are making decisions from is wrong. Unauthorized transactions and fraud go undetected because the bank statement is the control that would have exposed them. Auditors treat unreconciled cash as a red flag, and tax filings built on those numbers may need amending. For ecommerce sellers, there is a margin cost too: platform commissions and processing fees that are never separated from revenue quietly overstate gross margin on every channel.
What is the difference between bank reconciliation and accounts receivable reconciliation?
Bank reconciliation confirms the cash you have; accounts receivable reconciliation confirms the cash you are owed. Bank reconciliation compares the general ledger cash account to the bank statement, accounting for outstanding checks, deposits in transit, and fees. Accounts receivable reconciliation compares the accounts receivable subledger, usually the aging report, to the accounts receivable control account in the general ledger. For an online store, the first tells you whether the Stripe and Shopify payouts that reached your bank are fully recorded; the second tells you whether unpaid invoices and unsettled orders are stated correctly.
How often should a business reconcile its accounts?
Businesses should reconcile their accounts at least monthly, timed to the bank and credit card statement cycles. High-volume ecommerce sellers benefit from weekly reconciliation, because platform payouts arrive on staggered schedules and a month of unmatched transactions across four channels is far harder to unpick than a week of them. During peak seasons, daily reconciliation of the clearing accounts keeps the backlog from building. Businesses preparing for an audit, a funding round, or a sale should keep accounts reconciled continuously, since diligence teams ask for current reconciliations, not year-old ones. How often should a small business reconcile books? Monthly is sufficient where there is one bank account and low transaction volume, moving to weekly once a second sales channel is added.
How do you solve an out-of-balance reconciliation?
To solve an out-of-balance reconciliation:
- Check each transaction for accuracy, ensuring that all entries have been recorded and match the corresponding documents.
- Ensure no transactions were missed or recorded twice.
- Make sure all totals add up and that transactions are recorded under the correct dates.
- Make adjustments for any overlooked fees, incorrect entries, or mathematical errors.
Can you reconcile an expense account?
Yes, you can reconcile an expense account. This involves:
- Ensuring all expenses recorded in the account match the actual money spent, as shown in receipts, invoices, and bank statements.
- Reviewing the classifications and amounts of expenses to ensure they are recorded in the appropriate categories and amounts.
- Finding and correcting any inaccuracies, such as misclassifications, duplicate entries, or missing transactions.
What is the difference between reconciling cash received and recognizing revenue?
Reconciling cash received confirms the money arrived; recognizing revenue determines when you can report it as income. A customer pays $1,200 upfront for an annual subscription. Cash reconciliation ties that $1,200 to the Stripe payout and the bank deposit in the month it was collected. Revenue recognition under ASC 606 reports $100 per month across twelve months, holding the remainder in deferred revenue on the balance sheet. Both need reconciling: the cash account against the bank, and the deferred revenue account against the billing system’s recognition schedule. Synder RevRec builds those schedules for subscription businesses so the two views stay tied to each other.
Disclaimer: This article provides a general overview of reconciliation and is intended for informational purposes only. It’s not intended as professional advice. Accounting practices and regulations can vary widely, so it’s important to consult a qualified accounting professional who can provide advice tailored to your specific circumstances and ensure compliance with applicable laws and standards.
Excellent article! Thanks for explaining how to reconcile transactions.
Thank you very much, David! We’re glad you found the article helpful.